Democratic Win Reshapes Debt Ceiling: US Bond Market at the Edge of Uncertainty
Baca dalam 60 detik
- Kemenangan Demokrat pada pemilu sela 2026 memberi mereka kendali atas Kongres, memicu spekulasi bahwa kenaikan plafon utang akan dijadikan alat tawar-menawar kebijakan.
- Pasar keuangan AS bersiap menghadapi volatilitas karena Demokrat berpotensi menuntut pembalikan pemotongan Medicaid dan pembatasan tarif sebagai syarat persetujuan.
- Batas waktu efektif diperkirakan jatuh pada kuartal IV 2027, dan risiko gagal bayar teknis dinilai lebih tinggi dari episode sebelumnya.
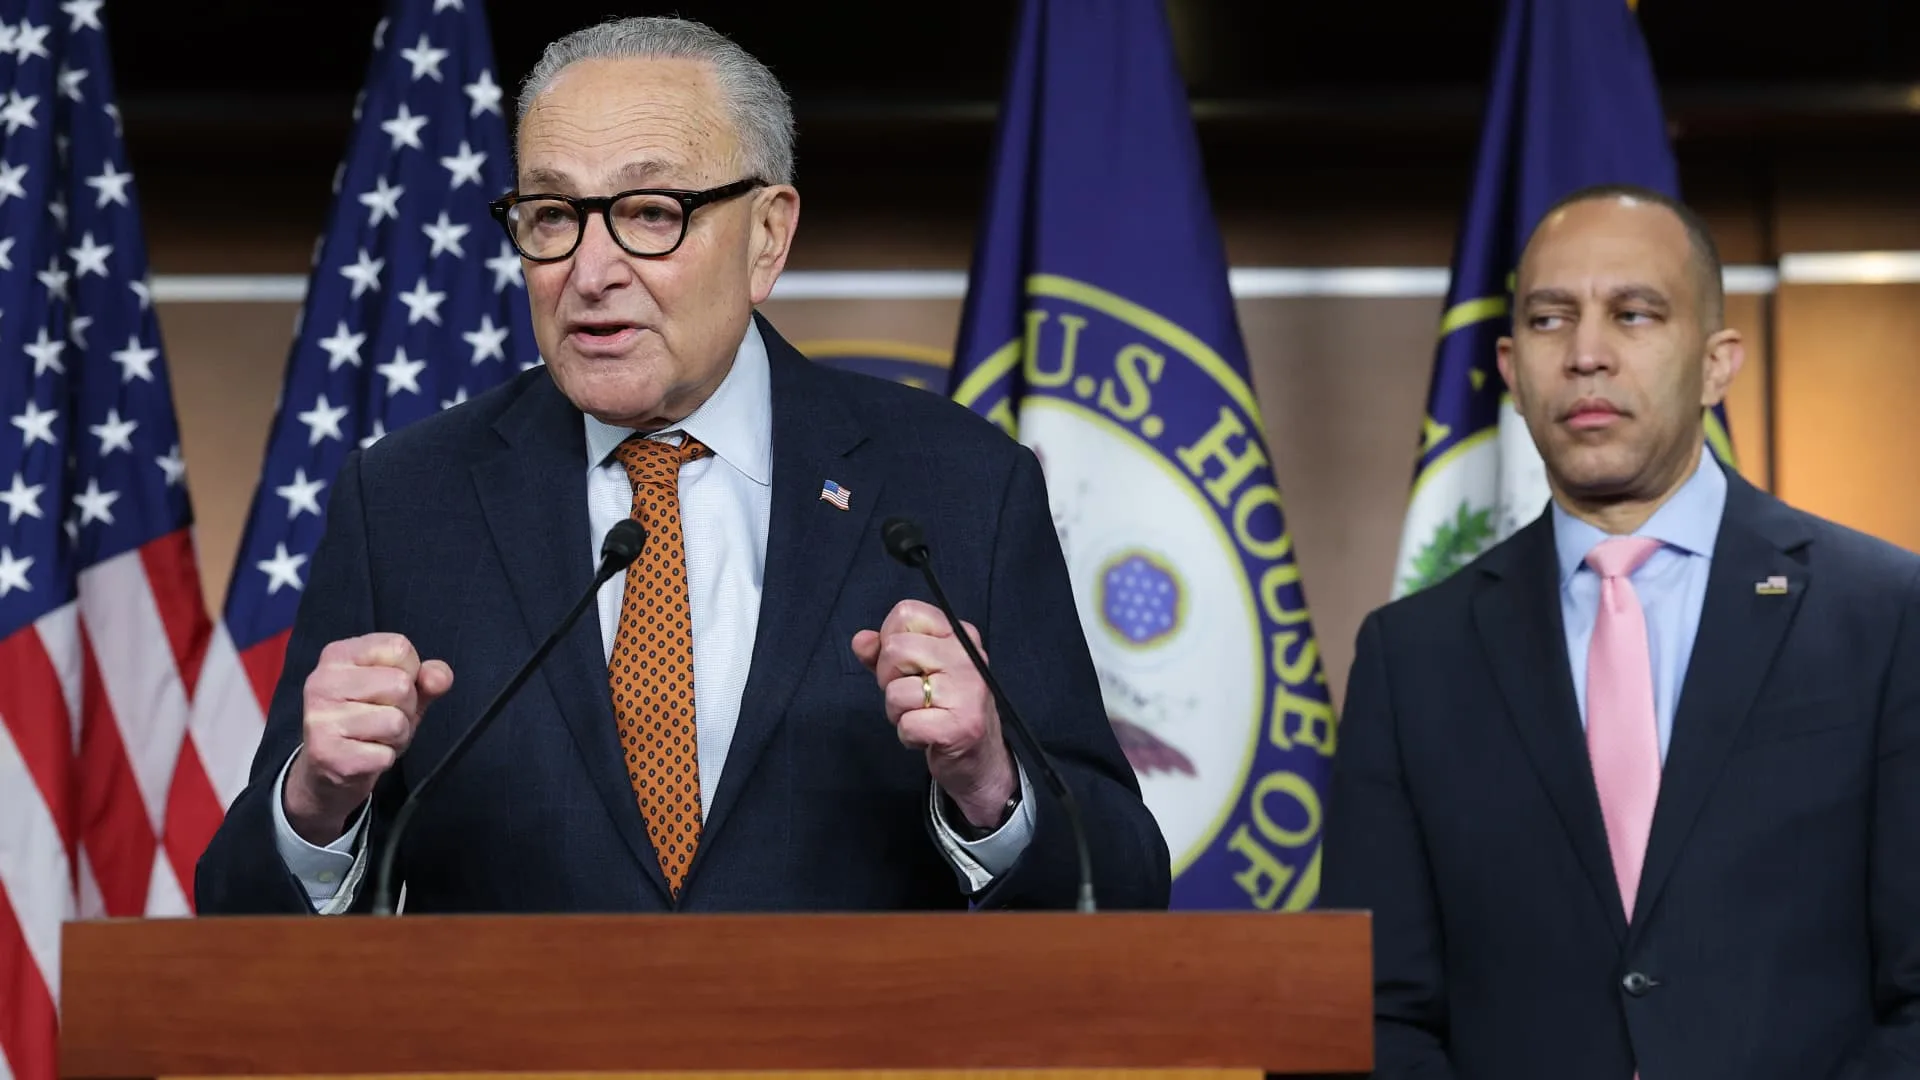
The Democratic Party's sweeping victory in the United States midterm elections on Tuesday night immediately redrew the political risk map that market players fear most: the federal debt ceiling. For the first time in decades, it is the Democratic Party—not the Republican Party—that will hold control of Congress when the government's borrowing limit comes back into focus. As a consequence, next year's budget negotiations could turn into a fierce battle that shakes the Treasury bond market, valued at trillions of dollars.
Until now, raising the debt ceiling has always been a moment for the Republican Party to pressure a Democratic president into cutting spending. Now the roles are reversed. With a majority in Congress, the Democrats have a golden opportunity to force President Donald Trump to make concessions on policies that have long been their priorities, from restoring health budgets to curbing tariff policy and military involvement in Iran. However, because the bargaining position lies with the left, the final deal is actually likely to raise government spending rather than cut it—an irony acknowledged by several analysts.
"They are still imagining a Biden-Harris figure in 2024," said Aniket Shah, head of the Washington policy team at Jefferies, as quoted by CNBC. "I think the market has not yet realized how aggressively the Democrats plan to confront 2027." Shah added that the Democrats will seek to embarrass the White House and accumulate as much leverage as possible.
The bond market is already showing vulnerability. Long-tenor Treasury yields have risen in recent weeks due to inflation expectations and policy uncertainty. According to Robert Sockin, chief US economist at PGIM, this debt ceiling episode could resemble the longest government shutdown in history, which occurred in 2025. "It is not our base case, but the risk of a technical default by the government is now higher than before," he said. He warned that further yield increases and a negative reaction in the stock market are highly likely if negotiations pass the X-date.
Several compromise scenarios are beginning to be discussed in Washington. Goldman Sachs analysts said the Democrats could tie a debt ceiling increase to restrictions on tariff policy or efforts to end the war with Iran. Meanwhile, George Pollack of Signum Global Advisors sees an opportunity for the Democrats to propose raising the corporate tax rate in exchange for approving the debt ceiling—a step he said Trump might accept because the president is known to be flexible on similar issues.
On the other side, the Republican Party still hopes to raise the debt ceiling before the new Congress is sworn in, taking advantage of the lame-duck session. However, that effort requires budget reconciliation that demands party unity—something difficult to achieve given the fragile and divided Republican majority. Trump himself has urged his party to resolve the issue in the coming weeks, but the chances are slim.
For Indonesia, turmoil in the US bond market is not merely a spectacle. As a developing country dependent on foreign capital flows, rising US Treasury yields could trigger capital outflows from emerging markets, including Indonesia. A weaker rupiah and pressure on government borrowing costs become real risks if volatility continues. Global investors tend to shift to safe-haven assets when uncertainty looms over US bonds, and the impact will be felt all the way to Jakarta.
The question now is: how far are the Democrats willing to go? If they choose to hold back a debt ceiling increase until past the deadline, it is not only US financial markets that will be shaken, but also the still-fragile global economy. In the coming months, the public will watch whether this brinkmanship-style negotiation ends in a compromise as usual, or instead creates the bad precedent that has so far been avoided.