Apple Margins Under Pressure, a Warning Signal for Global Technology Supply Chains
Baca dalam 60 detik
- Apple mencatat pendapatan kuartalan di atas ekspektasi, tetapi proyeksi margin kotor yang lebih rendah memicu aksi jual saham.
- Kenaikan harga komponen memori dan tarif menjadi penyebab utama melemahnya profitabilitas, meski pendapatan iPhone dan Mac tetap tumbuh.
- Kinerja Tiongkok yang solid dan ekspansi layanan yang melambat menjadi sorotan investor menjelang kuartal liburan.
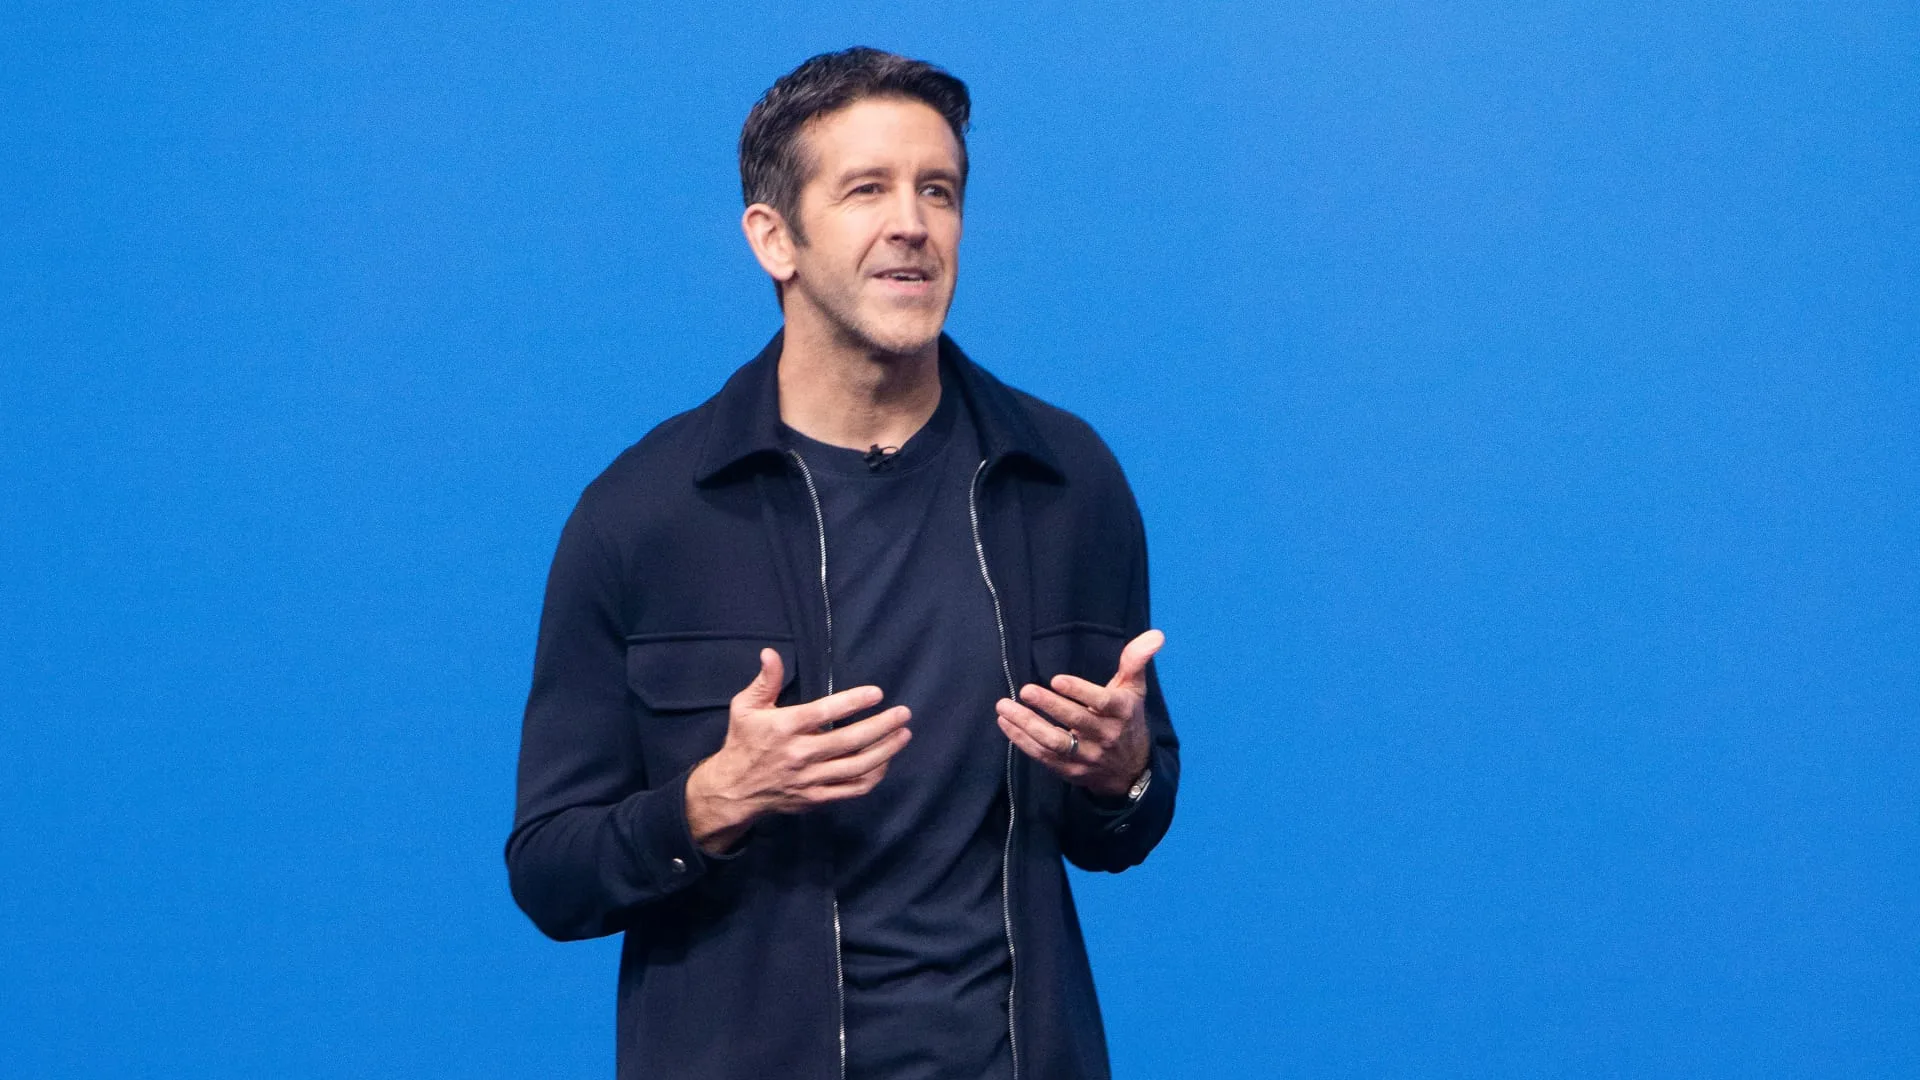
Apple Inc. reported fiscal fourth-quarter 2026 revenue of US$114.48 billion, beating analysts' estimate of US$113.39 billion, but its gross margin projection for the December quarter of just 45–46 percent—below the 46.3 percent consensus—immediately triggered a share price correction of about 3 percent in after-hours trading. The report marked the first time CEO John Ternus led an earnings presentation since succeeding Tim Cook on 1 September 2026.
Although revenue rose 12 percent year-on-year, component cost pressure loomed behind the result. Apple acknowledged that memory costs in the September quarter were higher than in the June period, and product price increases—including US$100 on the iPhone—only partly offset that pressure. The 47.9 percent gross margin was in fact slightly above expectations, but that figure already includes the impact of about 1 percentage point from tariff refunds; without that factor, the margin would have fallen below market expectations.
On the product side, the iPhone still accounted for more than half of total sales, with 17 percent growth. However, this quarter's report included only eight days of iPhone 18 Pro sales, while the iPhone Duo—a US$2,000 foldable device—only became available on 23 October, so its contribution was not yet felt. The Mac division was the star with a 24 percent surge, driven by MacBook Neo and MacBook Pro sales, while the iPad slumped with a decline of more than 10 percent, the worst performance among all product lines. Ternus blamed supply constraints and a difficult comparison with the same period last year.
Greater China posted 21 percent growth to US$17.53 billion, one of the bright spots amid the global economic slowdown. Unfortunately, the services business that has long been the profitability engine grew by less than 10 percent—its slowest growth since 2022. The slowdown raises questions about how much room Apple has to monetize its ecosystem, especially as investors await whether the Siri artificial intelligence features will become a new revenue source. Ternus said the company has "many opportunities" for monetization, including through hardware upgrades, but did not detail a concrete strategy.
Amid a wave of capital spending by other technology giants on AI infrastructure, Apple has instead chosen a conservative approach. Capital spending this quarter was just US$2.24 billion, far below the US$3.33 billion estimate. The move sets Apple apart from Microsoft, Google, and Meta, which are pouring hundreds of billions of dollars into AI data centers. However, Needham analyst Laura Martin cautioned that Apple has "bet everything" on the relevance of the smartphone, while competitors are beginning to experiment with new device form factors. "Almost every AI company will try to change that device form factor," she said, while recommending holding the stock.
"We saw higher memory costs than in the June quarter, and that was partly offset by the benefit of inventory ownership and lower non-memory component costs," Ternus told CNBC.
Pressure on margins also comes from the macro environment. According to IDC, the global smartphone market is expected to shrink by nearly 17 percent this year in terms of shipments, while the PC market fell 11 percent. Memory and component shortages have forced many manufacturers to raise prices or cut specifications, and consumers are holding off on buying their older devices. On the other hand, Apple remains one of the few technology giants that has not weighed down its balance sheet with large capital spending, so its cash position remains strong. However, its dependence on the phone cycle and vulnerability to component cost fluctuations will test Ternus in his first year.
For Indonesia, this dynamic deserves attention. Apple does not yet have a manufacturing plant in the country, but its products dominate the premium segment, and global pricing policy—including increases due to component costs—could affect local consumer purchasing power as well as telecom operators' strategies in offering bundling packages. In addition, a strained global supply chain could affect device availability in the Indonesian market, especially ahead of the year-end shopping season. The government itself is pushing downstream development of electronic components, and the cost pressure Apple is experiencing could be a mirror of how crucial mastery of memory and semiconductor technology is for the domestic industry.
Going forward, the market will watch whether this conservative margin projection is merely a temporary disruption from the memory price cycle, or a signal that Apple's era of fat margins is beginning to end. The iPhone Duo launch in the current quarter will be the real test, especially after reports emerged that the foldable device's screen cracked under normal use—which Apple acknowledged affected only "a small number" of devices. If Ternus can reverse that perception and maintain momentum in China, pressure on the stock may ease. However, if component costs keep rising and services growth slows, Apple may need to seek new, more aggressive sources of growth beyond hardware.